

Trade Distribution Analysis
Trade Distribution Analysis: Read Your Strategy Beyond Win Rate
Learn how to run a trade distribution analysis: build the histogram of your trade results, read skew and fat tails, and avoid sample-size and bias traps.
Learn how to run a trade distribution analysis: build the histogram of your trade results, read skew and fat tails, and avoid sample-size and bias traps.
How to backtest a Bollinger Bands strategy: define entries and exits, set costs, read the metrics, avoid overfitting, and validate before risking capital.
Learn how to backtest a scalping strategy realistically: model spread and slippage, avoid look-ahead bias, size your sample, and validate out of sample.

Learn how intraday backtesting works: choosing data, defining rules, multi-timeframe testing without look-ahead bias, the metrics that matter and the errors that fool traders.

How to run a Heikin Ashi backtest you can trust: set the rules, avoid synthetic fills and look-ahead bias, add costs, and check results across markets.

Learn what the Ulcer Index measures, how to calculate it step by step, how to read the number, and how to use it with the Martin ratio to judge a strategy.

Evidence-based trading means testing every rule on historical data before risking capital. Learn the hypothesis, backtest, metrics and pitfalls that matter.

Renko backtests often look better than live trading. Learn the look-ahead and tick-data traps, how to model costs, and a clean process to test Renko honestly.

Learn how to optimize a trading strategy on historical data: pick parameters, set ranges, judge metrics, and test for overfitting before risking real capital.

Backtesting tests rules on past data. Paper trading tests you and those rules in live markets. Learn what each proves, where each fails, and the best order.

Trailing stop or profit target? See how each exit works, where each fails, and how to test both on your own strategy before risking real capital.

Backtest an RSI strategy the right way: pick rules, include costs, avoid overfitting, validate out of sample and read win rate, profit factor and drawdown.

Learn how the Sharpe ratio works in trading, what counts as a good number, and when Sortino or Calmar tells you more, with a worked example.

A practical strategy validation checklist for traders: ten checks, from look-ahead bias to costs and Monte Carlo, plus a sign-off gate to reject weak strategies.

How to backtest a moving average crossover or golden cross honestly: rules, costs, look-ahead bias, out-of-sample checks and what a real result looks like.

Overfitting makes a backtest look great and fail live. Learn the warning signs, the math behind false winners, and a practical checklist to test strategies honestly.

Learn how to backtest price action with realistic tick or bar data, catch overfitting and selection bias, and validate results before risking capital.

Learn how traders can forward test a strategy with five setup checks, locked rules, and validation methods such as PBO, CPCV, and walk forward analysis.

Turn discretionary Smart Money Concepts into auditable rules, then test for lookahead bias, data mining, costs, and slippage before trusting a backtest.

Learn how HMMs, clustering, and volatility filters classify market regimes, then validate signals with walk forward backtests before changing trading risk.

Test a swing trading backtest with point in time data, realistic fills, walk forward validation, and five diagnostics to expose false edges.

Learn how backtesting data length varies by trade frequency, then estimate a sound sample using market regimes, trial counts, and the Deflated Sharpe.

Turn order block rules into code, then test with realistic costs, out of sample data, and walk forward checks. Track profit factor and drawdown.

Use MAE and MFE analysis to set stops by percentile, compare excursions normalized by ATR, and log journal fields for evidence based reviews.

Calculate trading expectancy with concrete examples ($7/trade, 0.09R). Include costs, avoid overfitting, and validate your edge with realistic backtests.

Evidence-first guide to risk reward ratio for retail traders: calculate R:R, apply the 2% sizing rule, and run a six step backtest with Backtestify to...

Trader-focused, implementation-first guide to turn Kelly Criterion math into validated position sizes. Learn fractional Kelly, portfolio constraints, and...

Backtest first stop loss optimization for algo developers and quants. Use walk-forward validation, Monte Carlo stress tests, and conservative slippage...

Learn which methods, block lengths, and OOS checks to run—and why 5,000+ paths reveal true drawdown, ruin probability, and reproducible risk limits.

Evidence first guide: turn next candle signals into tested probabilities. Combine candle features, volume and trend filters, then backtest before risking...

Learn an execution first view of profit factor: compute it after costs, check trade count and equity curve, and verify out of sample results before...

Convert discretionary ICT setups into plain English AI assisted rules, run walk forward validation, and check execution across engines before risking capital.

An 8 Step TradingView Pine Script backtest checklist to avoid repaint, fill, and trailing stop bugs. Export to CLI for reproducible analysis and deeper...

Position sizing methods with math examples, Kelly and Bayesian cautions, and a workflow that tests first. Start with a 0.5–1% baseline before risking live...

An execution-first checklist for developers and algo traders: eight concrete steps to map exchange specs to fills, model 1 tick per-side costs, and reach...

Practical walk forward analysis for algorithmic and retail traders. Implementation checks include purge and embargo controls, state resets, DSR and PBO,...

Simulation first guide to estimate and control risk of ruin with Monte Carlo and bootstrap percentiles (95th, 99th), concrete sizing rules, and evidence...

Learn how to calculate and validate risk adjusted returns using clear formulas, a reproducible Sharpe and Sortino example, and practical backtesting checks.

Diagnostic-first guide for quant teams to expose and fix look-ahead bias. Use T+1 shifts, timestamp audits, purged cross-validation, and a reproducible...

How data snooping bias inflates backtests, which tests (Reality Check, SPA) detect it, and practical backtesting steps and tools to expose overfitting...

Trader how-to: run walk-forward out-of-sample tests. Enforce purge gaps, lock parameters, and use Deflated Sharpe to expose backtest inflation.
Use a regulator-style, evidence-based workflow to backtest trading strategies: precise rules, realistic fills, out-of-sample validation, and paper trading...
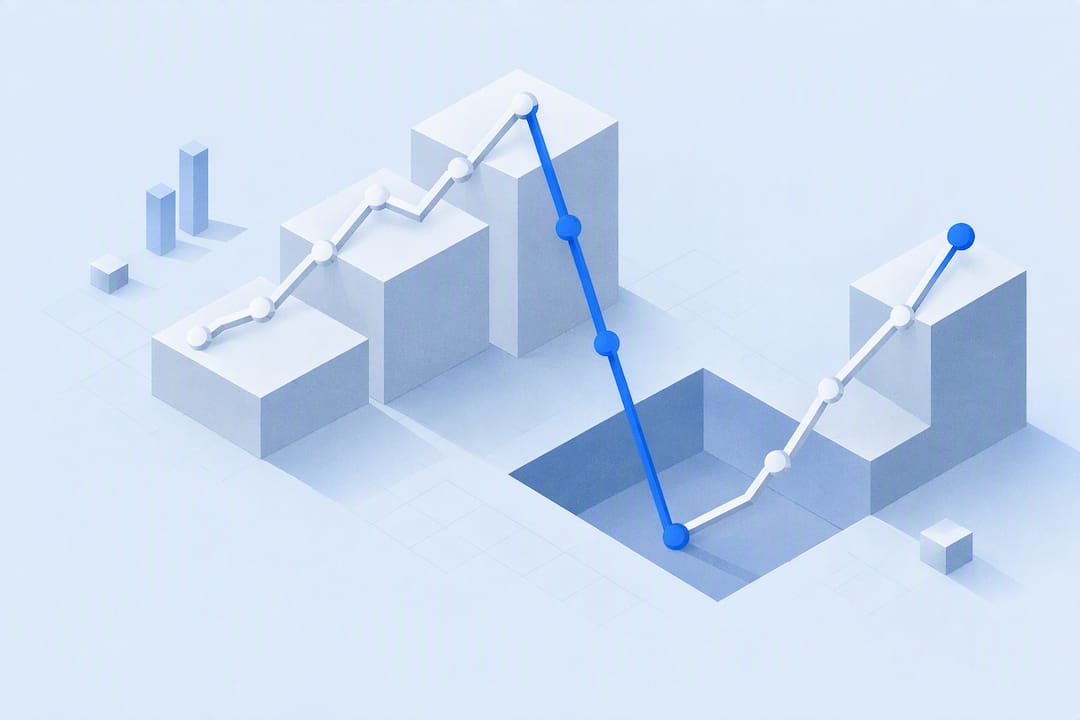
Calculate maximum drawdown, run backtest checks to expose hidden risk, and validate trading strategies with peak to trough examples.
Backtest options strategies using realistic fills, out of sample checks, and Monte Carlo stress tests. Try a free Backtestify account to run your first...